|
|
THE WEEKEND READ
Issue two · 17 October 2026
|
|
|
Added by our team on 17 October 2026 at $332. Value Picks are businesses we would hold with no sell
date, measured against the S&P 500.
|
Western Digital
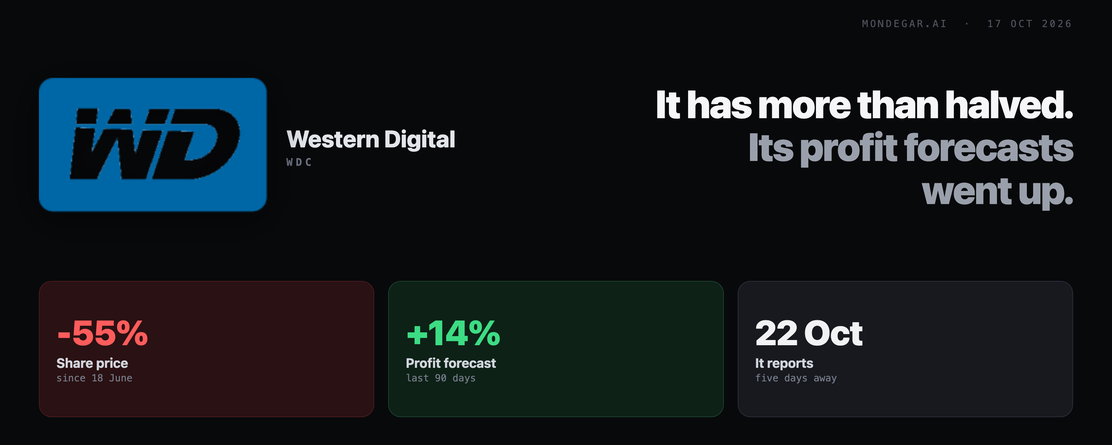
Has more than halved. Its profit forecasts went up.
WDC · $332.00 · market cap $124.3bn · 52-week range $117.23 to $799.87
Sources: Western Digital annual report filed 14 August 2026 · the eight quarterly releases to
3 July 2026 · LSEG · Argus · Morningstar · Nikkei · Mondegar
holdings, 13F and sentiment data
|
|
A Toshiba factory plan knocked 10 percent off the shares in one day. We ran the numbers on that fear, found the figure most screens get wrong, and set out how we would buy before results on 22 October. |
OUR CALL: Buy half now. Decide on the other half after 22 October. |
|
At 332 dollars, Western Digital costs about 10 times the profit analysts expect for the year to July 2028. That price already assumes the boom ends soon. Add the second half only if gross margin on 22 October is 55 percent or better. Keep the whole position small enough that another 50 percent fall would hurt but not harm you, because this stock has just shown it can do that. |
WHAT HAPPENED |
On 18 June, Western Digital closed at 746 dollars. By 16 October it closed at 332. That is a fall of 55 percent in four months, at a company whose sales have grown in each of the last five quarters. |
Two days stand out. On 6 August, the day after results, the shares fell 13 percent, even though the company beat its own forecast. Morningstar's explanation is that it shipped a little less storage than hoped. Then on 2 October, Nikkei reported that Toshiba, the smallest of the three companies that still make hard drives, will spend about 380 million dollars to double its output. Western Digital fell 10 percent that day, on its heaviest trading in two months. |
From $746 to $387 in four months. Two days stand out. |
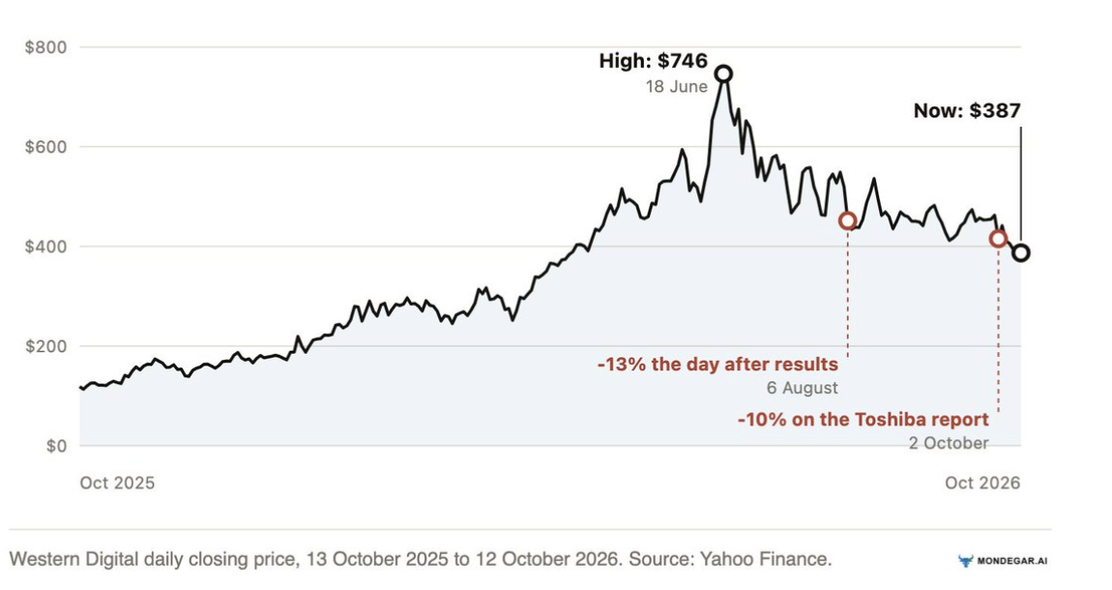 |
Western Digital daily closing price, 13 October 2025 to 12 October 2026. Source: Yahoo Finance. It has since fallen to $332. |
Over the same 90 days that the shares fell 30 percent, the analysts who follow the company went the other way. Their forecast for profit in the year to July 2027 rose 13.6 percent, to 20.52 dollars a share. Their average price target rose 18 percent, to 668 dollars. Ninety days ago the target and the share price were the same number, about 555. Today they are 270 dollars apart. |
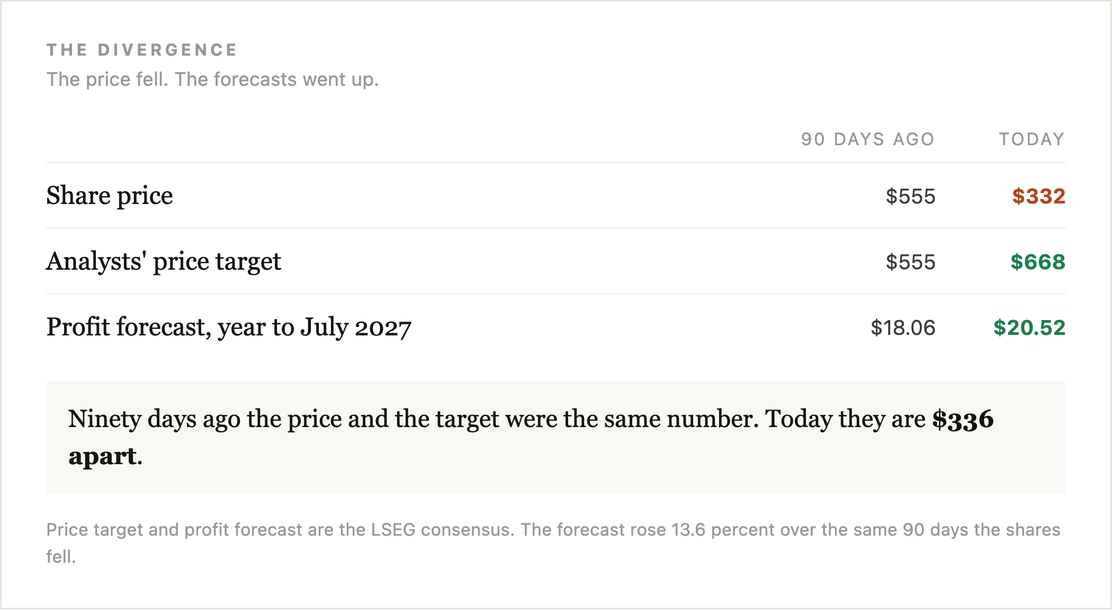 |
Price target and profit forecast are the LSEG consensus, 11 October 2026. |
Either the analysts are late, or the market is early. Here is how we would tell the difference. |
WHAT WESTERN DIGITAL IS NOW |
Until February 2025, Western Digital also owned SanDisk, the flash memory maker. It spun SanDisk off and is now a hard drive company and nothing else. Hard drives are the spinning disks that still hold most of the world's data, because they are far cheaper per terabyte than flash. Morningstar puts the gap at six to seven times. The company says 80 percent of the data in the giant cloud data centres sits on hard drives. |
That is who buys them. Of last year's 12.9 billion dollars of sales, 89 percent went to cloud companies, most of them building for AI. Argus reports the company is sold out for 2026 and 2027, and management says it is now negotiating supply contracts that run to 2031. |
Prices tell the same story. In the quarter to July, the average price per terabyte was up by what the finance chief called "high teens" percent. For five quarters in a row sales have risen, and for eight in a row so has the share of each sales dollar the company keeps as gross profit, from 37 cents to 54. |
Every quarter it keeps more of each dollar. The company expects 55 to 56 cents next. |
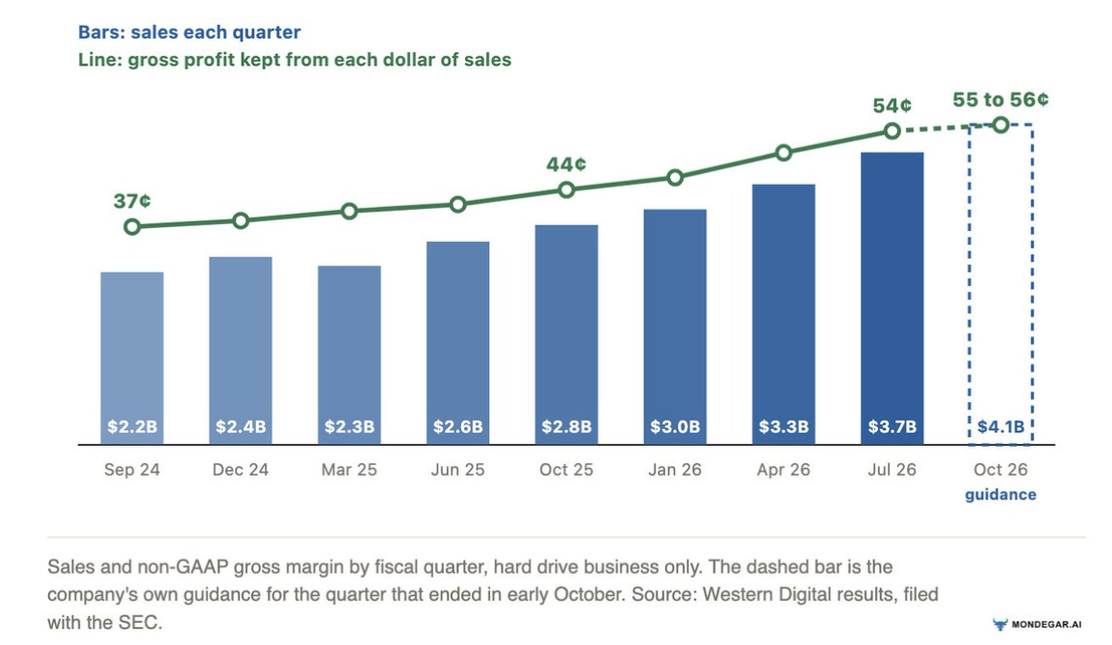 |
Sales and non-GAAP gross margin by fiscal quarter, hard drive business only. The dashed bar is the company's own guidance. Source: Western Digital results, filed with the SEC. |
For the quarter that just ended, the company has guided to 4.1 billion dollars of sales and 4 dollars of profit a share. It has beaten its own profit guidance in each of the last four quarters. |
Sales, margins, prices and contracts are all still moving the right way. The share price is the only thing that turned. |
THE NUMBER MOST SCREENS GET WRONG |
Look Western Digital up almost anywhere and you will see a profit margin of 72 or 73 percent and a price of about 16 times earnings. Neither is the real picture. |
Last year's reported profit was 24.28 dollars a share. About 14 dollars of that came from one-time items, mostly a 6.5 billion dollar gain on the SanDisk shares Western Digital kept after the split and later used to pay off debt and buy back its own stock. Those shares are all gone. That profit will not come again. |
The profit from making and selling drives was 10.22 dollars a share. On that, the shares cost 38 times last year's earnings, not 16. On analysts' forecast for this year it is 18.6 times, and on next year's, 12. |
Reported profit was $24.28 a share. Only $10.22 of it came from selling drives. |
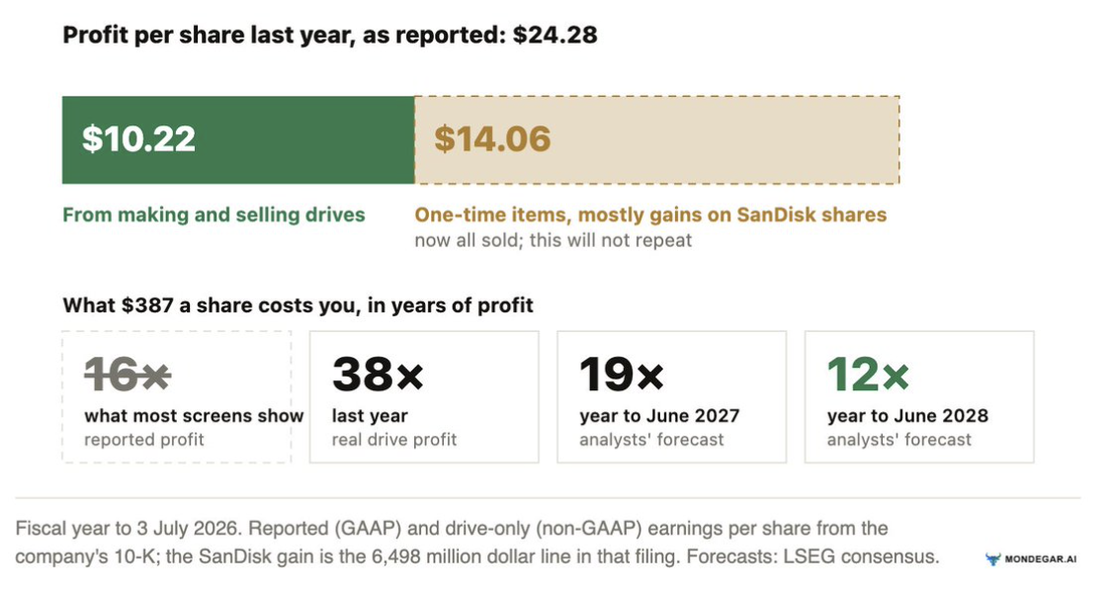 |
Fiscal year to 3 July 2026. Reported (GAAP) and drive-only (non-GAAP) earnings per share from the company's 10-K; the SanDisk gain is the 6,498 million dollar line in that filing. Forecasts: LSEG consensus. |
So the stock is not as cheap as the screen says, and not as dear as 38 times suggests. What you are really buying is the next two years of profit. That is why the question that moved the price this month is the right one to ask. |
IS TOSHIBA A REAL THREAT? |
Toshiba has a little over 10 percent of the hard drive market by capacity and, according to Nikkei, wants 30. Doubling its output by March 2028 would add roughly 10 percent of today's market. |
Now set that against demand. Western Digital's chief executive says demand for storage is growing at 25 percent a year or more. If that holds until March 2028, the world will need about 38 percent more drive capacity than today. Toshiba's new factory fills about a quarter of that. The rest still has to come from Western Digital and Seagate. |
Toshiba's new factory fills about a quarter of the new demand. |
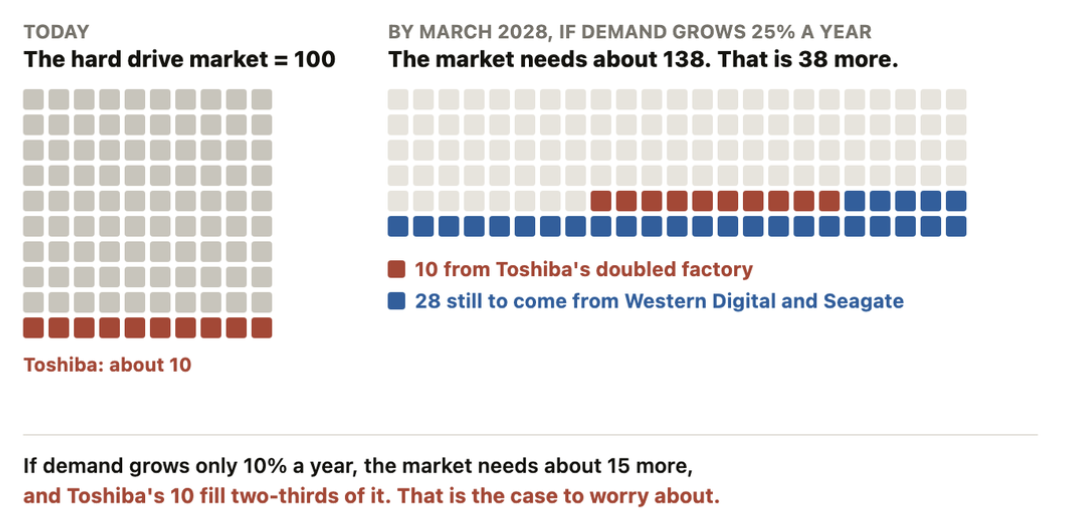 |
If demand grows only 10% a year, the market needs about 15 more, and Toshiba's 10 fill two-thirds of it. That is the case to worry about. |
So Toshiba alone does not break the story. Toshiba plus slower demand would. If demand grows 10 percent a year instead of 25, Toshiba's extra drives fill about two-thirds of the new need, and that is how price wars start. Watch demand, not Toshiba. |
Toshiba alone does not break the story. Toshiba plus slower demand would. |
WHAT THE EXPERTS SAY |
At $387, the price sits below even the most cautious value. |
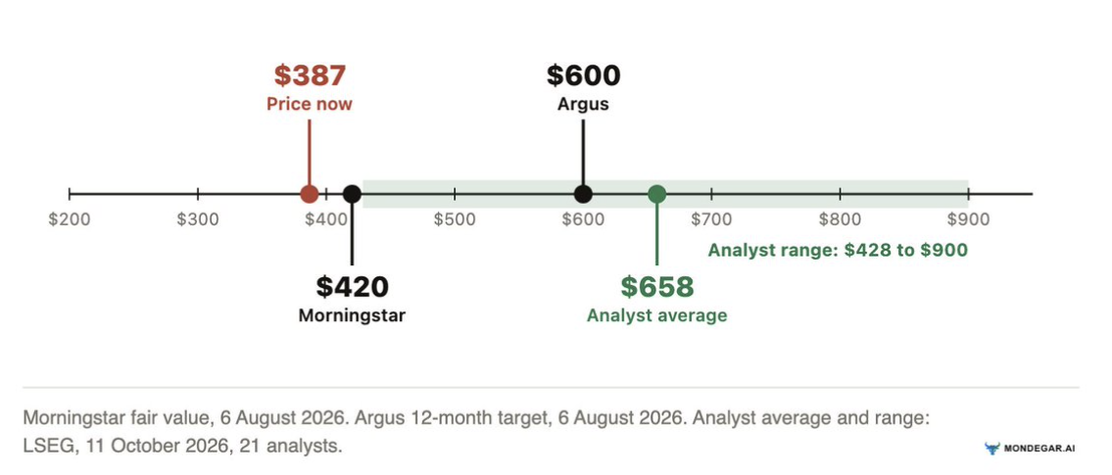 |
Morningstar fair value and Argus 12-month target, 6 August 2026. Analyst average and range: LSEG, 11 October 2026, 21 analysts. The price is now $332. |
They do not agree, which is useful. Of 27 analysts tracked by LSEG, 20 say buy, 7 say hold and none say sell. Argus, which rates it a buy, set a 600 dollar target in August. |
Morningstar is the sceptic, and worth hearing. It values the shares at 420 dollars and says Western Digital has no lasting competitive edge, because a hard drive is a commodity and every boom in this industry has ended in a bust. It assumes that by 2029 the shares will deserve only nine times earnings. MarketEdge, which reads only the price chart, says avoid for now, because the shares are still falling. |
| LSEG analyst average: Buy (20 of 27), $668 | | Argus: Buy, $600 | | Morningstar: Fairly valued, no moat, high uncertainty, $420 | | MarketEdge (chart only): Avoid | | Price now, $332 |
|
WHAT COULD GO WRONG |
The cycle. Hard drives have always been boom and bust. In fiscal 2023, before the split, Western Digital lost 1.7 billion dollars. Nobody has yet shown this time is different. They have only shown it is not over. |
Three customers. Three buyers took 44 percent of everything Western Digital sold last year. If one pauses its AI spending, the numbers show it at once. |
Seagate is ahead on the next drive. Morningstar says Seagate has a lead in the newer recording technology (HAMR) that makes bigger drives. Western Digital's 44 terabyte version arrives in the first half of 2027. |
Insiders are sellers. Executives and directors sold about 64 million dollars of stock this year and bought none. Most of it was pre-planned, but not all. |
It moves fast. It fell 13 percent on the day after results in August and 10 percent in January. On 22 October it can do either again. |
OUR CALL, IN FULL |
We think the market has priced in the end of the boom before there is any evidence of it. The company now has more cash than debt, about 1.6 billion dollars against 1.1 billion, and at the start of July it still had 3.26 billion dollars approved to buy back its own shares. |
But we would not put the whole position on one results day, for a stock that fell 13 percent on the last one. So: |
Now: buy half of what you intend to own, near 332 dollars.
After 22 October: buy the second half only if gross margin is 55 percent or better and management repeats that demand is growing 25 percent a year. |
If gross margin comes in below last quarter's 54.4 percent, do not add. That would be the first real sign that prices are turning, and it matters more than any Toshiba headline. |
Size it honestly. This share fell 55 percent in four months while the business was growing. Own an amount you could watch do that again. |
WHAT TO WATCH ON 22 OCTOBER |
Results come out after the market closes, with the call at 4.30 in the afternoon, New York time. Four numbers matter: |
Gross margin: the company guided to 55 to 56 percent. Below 54.4 is a warning. |
Storage shipped: last quarter was 231 exabytes, up 22 percent on a year earlier. Growth below that says demand is cooling. |
Contracts: any signed supply agreements for 2029 to 2031. |
Next quarter's guidance against the 4.77 dollars a share analysts expect. |
SEE IT FOR YOURSELF |
Everything above is on Mondegar, for Western Digital and for any other ticker you care to type. This is what the page looks like. |
Our read, scored against 45 Technology peers |
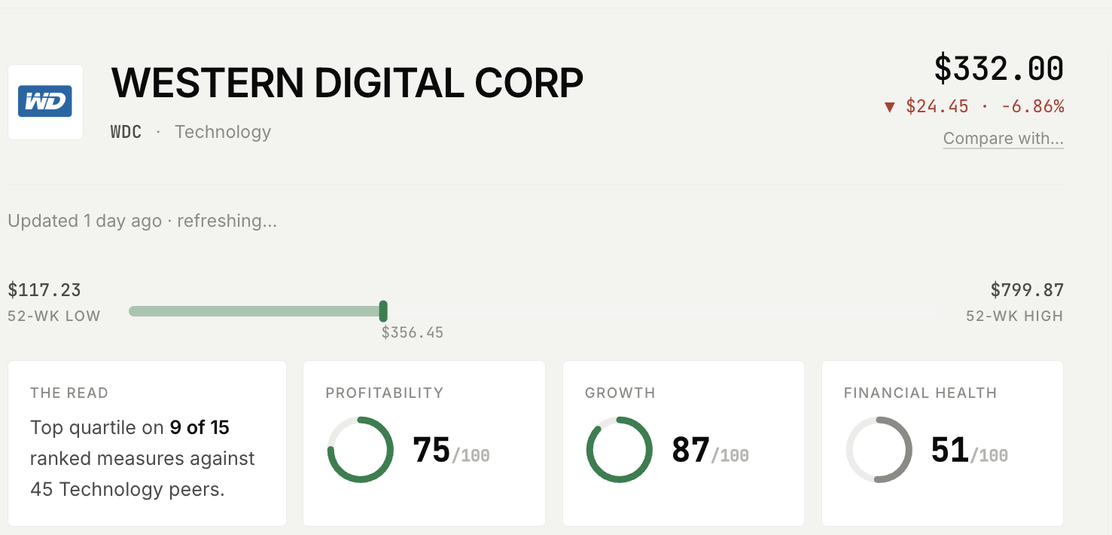 |
Top quartile on 9 of 15 ranked measures. Profitability 75, growth 87, financial health 51, each scored against the sector rather than in the abstract. |
The price, with its own averages |
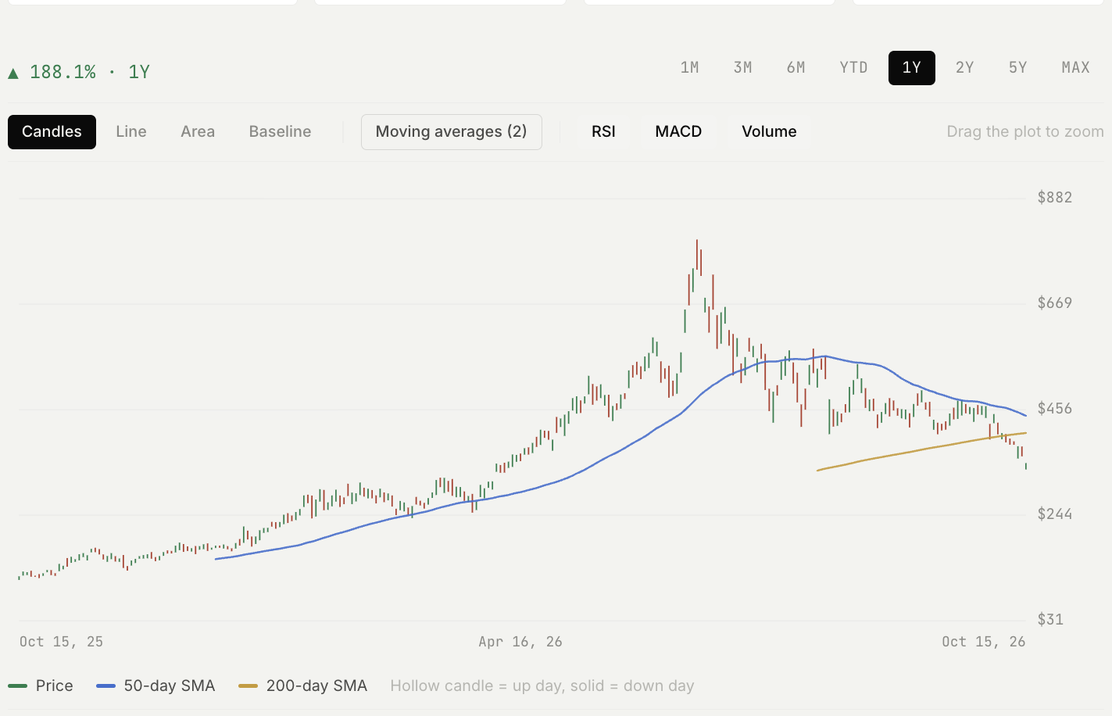 |
Candles, the 50 and 200 day averages, and any window from a month to twenty years. Drag the plot to zoom. |
Momentum, underneath |
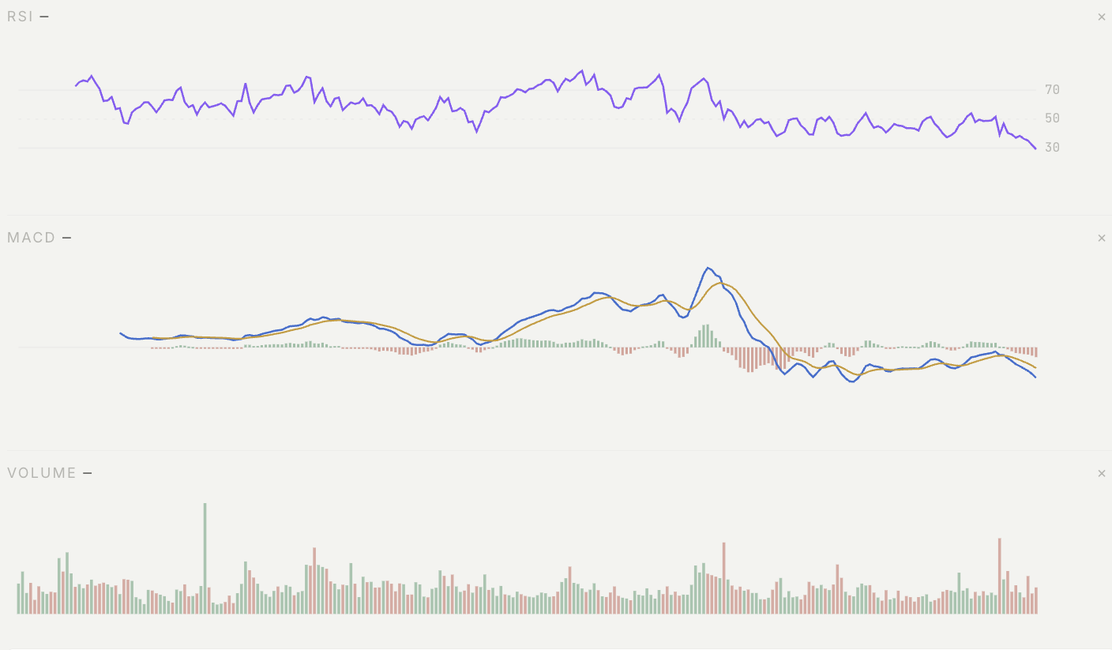 |
RSI, MACD and volume on the same timeline. RSI at 27 is the lowest it has been all year. |
Every number that matters, ranked against the sector |
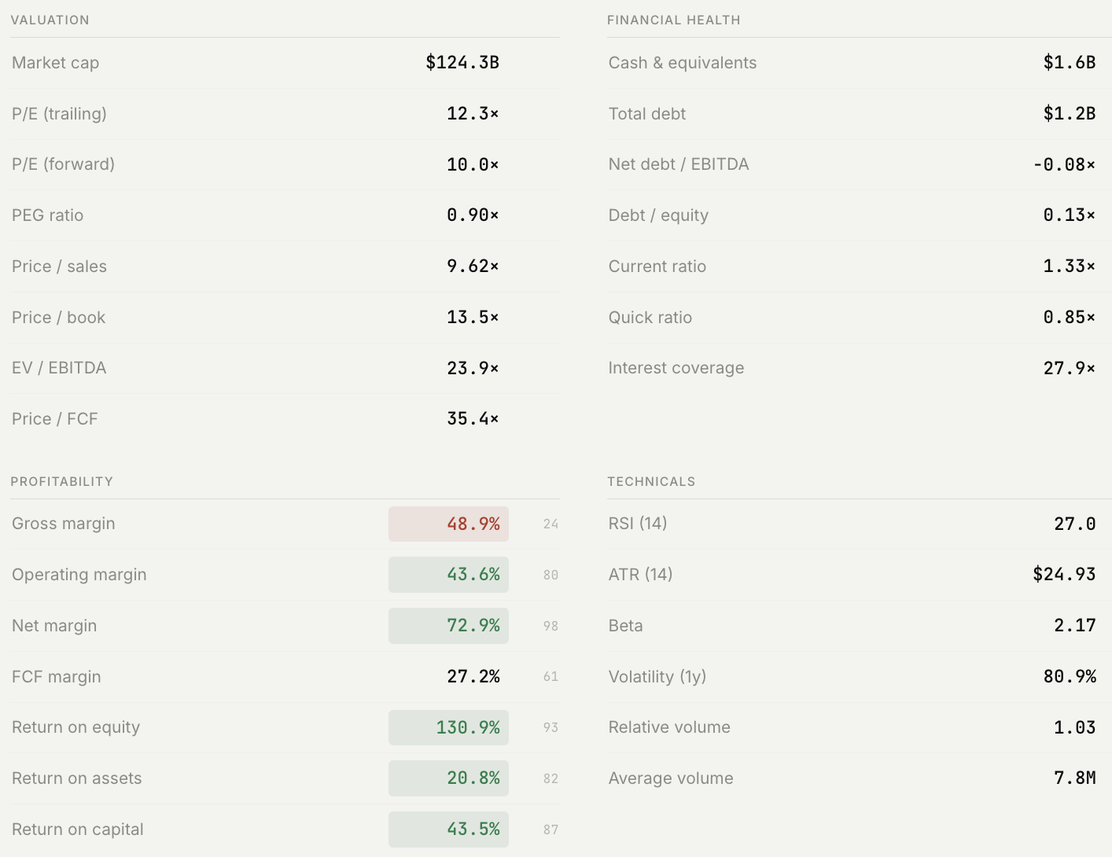 |
Tinted where a measure sits in its sector's top or bottom quarter. The small figure on the right ranks it against 45 Technology companies. |
Four years of the accounts, drawn |
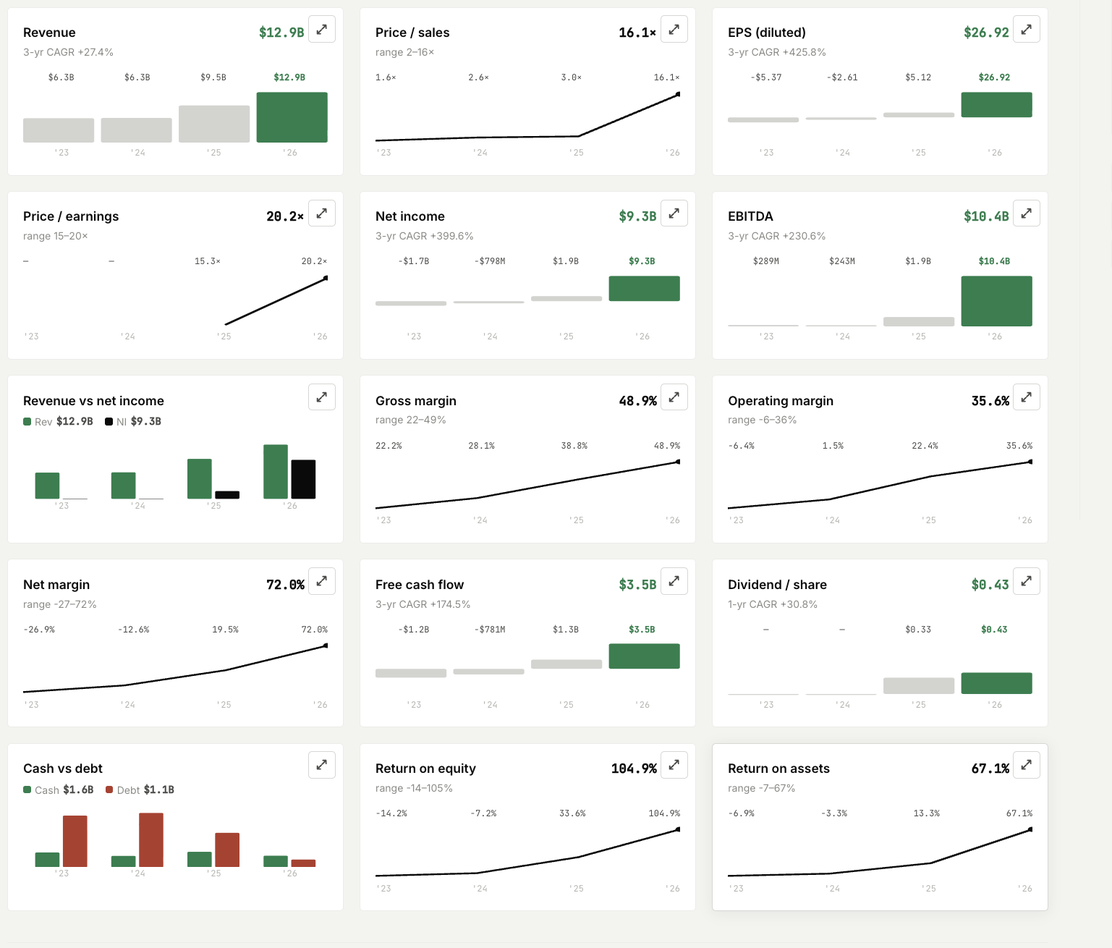 |
Revenue, earnings, margins, free cash flow, cash against debt and returns on equity and capital. Revenue has compounded 27.4% a year and free cash flow 174.5%. |
WHAT THE SMART MONEY DID |
This is the part you cannot get from a price chart, and it is the reason we looked at Western Digital at all. We track what the big funds actually filed, quarter by quarter. |
Smart Money, by 13F quarter |
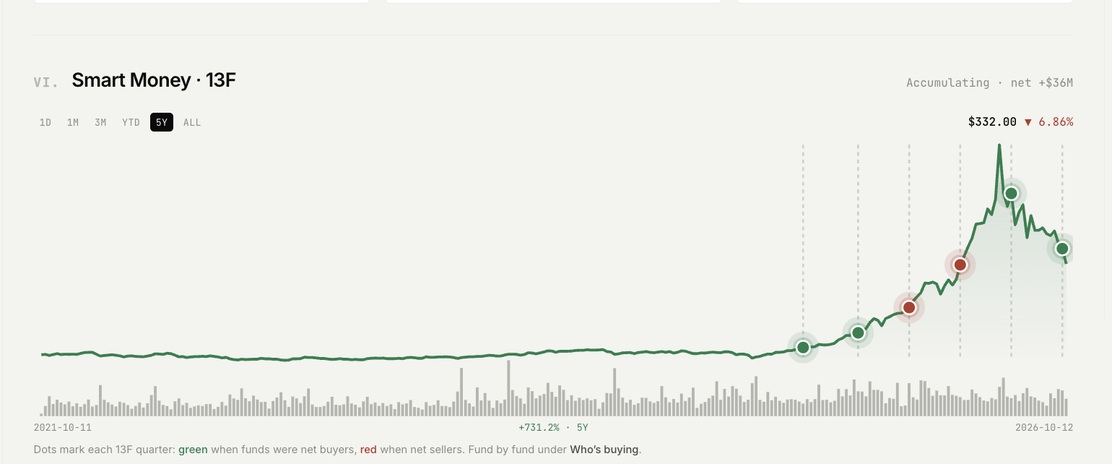 |
Green dots mark quarters when tracked funds were net buyers, red when net sellers. 13 tracked holders, $52.63bn, 82.4 million shares. |
Through the quarter in which the shares fell, the funds we track were net buyers, a net 51.6 million dollars. That followed a 7.21 billion dollar quarter of buying before it. |
| Citadel | +2,911,310 shares | +49.8% |
|
| Millennium | +257,409 shares | +35.1% |
|
| BlackRock | -2,815,609 shares | -7.9% |
|
| Bridgewater | -76,624 shares | -30.8% |
|
| Point72 | -843,251 shares | -76.0% |
|
They do not agree either. Citadel added half as much again to its position and Millennium a third, while Point72 cut three quarters of its holding and Bridgewater a third. Serious people sit on both sides of this, which is exactly why we are buying half and not all of it. |
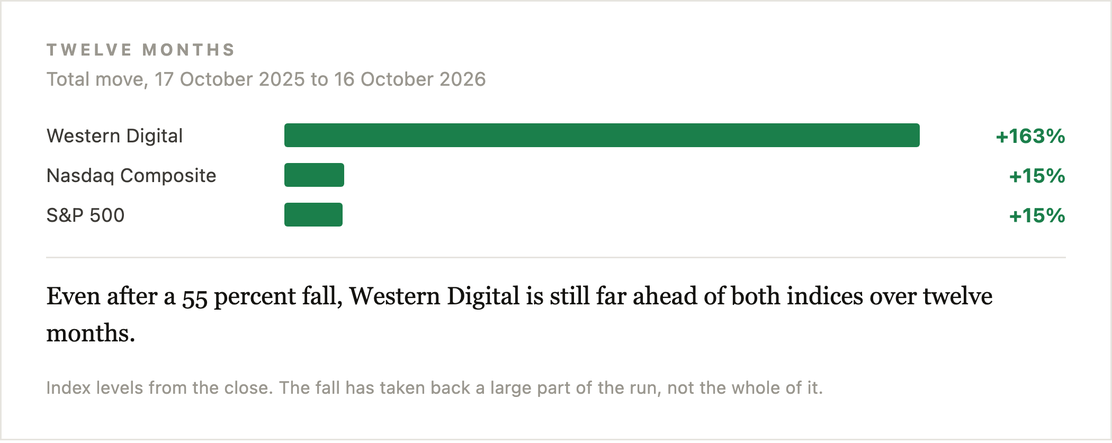 |
Even after the fall, Western Digital is far ahead of the S&P 500 and the Nasdaq over twelve months. |
Western Digital on Mondegar
Price, fundamentals, the funds that own it, and what Congress holds. |
Seagate on Mondegar
The other half of the duopoly, side by side. |
Our Ideas
Today's picks, each with the price, the reason and what would change our mind. |
HOW WE DID THIS |
Company figures are from Western Digital's filings with the SEC: the results releases for the eight quarters to 3 July 2026 and the annual report filed 14 August 2026. Reported profit of 24.28 dollars and drive profit of 10.22 dollars a share are the GAAP and non-GAAP figures in that report. Guidance and the 22 October date are from the company. Management quotes are from the 5 August call. Prices are Yahoo Finance closes to 16 October 2026. Consensus forecasts, targets and ratings are from the LSEG report of 11 October 2026. Morningstar's view is from its 6 August 2026 note, Argus from its 6 August note, and MarketEdge from its 9 October weekly. The Toshiba figures are Nikkei's, as reported on 2 October. The Toshiba-against-demand chart is our own arithmetic on those inputs, and it moves with the demand growth you assume. Insider sales are from every Form 4 filed from 1 January to 21 September 2026. Holdings and 13F flows are Mondegar data and lag the market by up to 45 days. |
Nothing here is advice to buy or sell. Please make your own decisions. |
|
Which company should we pull apart next?
This piece exists because a member asked for it. If there is a stock you own, or one you keep
meaning to look at properly and never do, reply and tell us. We will put it in the queue and do the
reading for you.
And every figure above traces to a filing. If you want the derivation, the model or the
sensitivities behind any of them, just ask and we will send the detailed analysis.
Request a company
Ask us for the detail
|
|
All of this lives in the app
The charts above, the 13F holdings, what Congress owns and six lists of stock ideas are all in the
Mondegar app, refreshed every day. There is a short note each morning about the shares you actually
own, and a button on every screen to ask it why. Free with your membership.
Get the Mondegar app
|
|
|
Nothing in this email is advice to buy or sell. Please make your own decisions. Data may be delayed or
inaccurate and 13F holdings lag up to 45 days.
MONDEGAR.AI
|